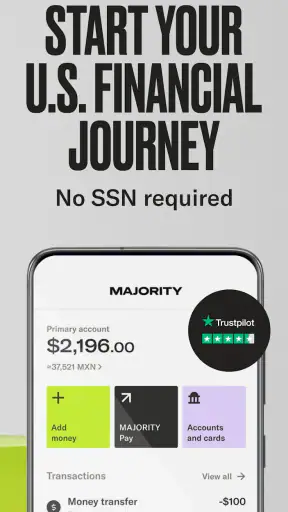
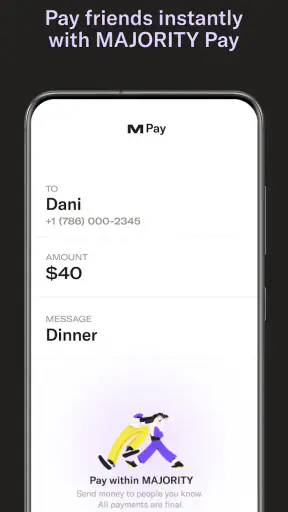
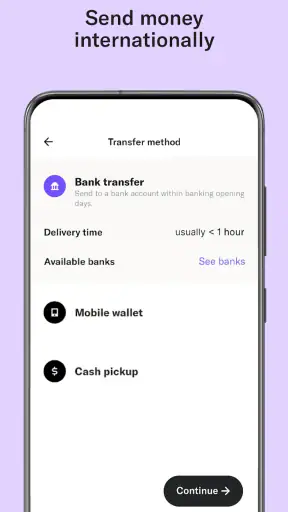
I found MAJORITY most interesting when I stopped treating it as just another mobile banking app. It is a finance app from MAJORITY USA, LLC built around a US account and debit card, with a particularly clear focus on people who want to manage money in the United States while also staying connected with family elsewhere. The promise is practical rather than flashy: open an account without an SSN, send money home, and use everyday banking tools from a phone.
After spending time with it, my view is that its strongest quality is focus. It does not try to be a complete replacement for every financial service. Instead, it aims to make a few important tasks approachable for people who may find traditional banking paperwork, unfamiliar terminology, or branch-based processes difficult. That makes it worth considering for newcomers, international families, and anyone who prefers handling basic banking from a handset.
It is free to download, carries an Everyone content rating, and has reached over one million installs. Its 4.7 average from around twenty-three thousand ratings suggests that many users find the overall experience useful. Still, a good rating does not remove the need to think about access, verification, device comfort, and whether its particular account model matches your situation.
How the app feels to read and navigate
A focused starting point for everyday banking
The first thing I noticed about MAJORITY is that its purpose is easier to understand than that of many larger banking apps. Traditional banking applications often place checking, savings, credit products, investing, insurance, alerts, and support into one crowded dashboard. MAJORITY presents a narrower path: an account, a debit card, money movement, and communication with people at home. For someone who is still learning the US financial system, that narrower scope can reduce mental overload.
This matters for readability. A person who is not comfortable with banking vocabulary does not necessarily need a screen full of financial products. They need to know where their balance is, how to use the card, and how to send money. I found that a simpler product concept makes it easier to build a routine: check the account, review recent activity, complete a transfer, and leave. The app is more approachable when used for those repeated tasks than when treated as a general-purpose financial command center.
The developer, MAJORITY USA, LLC, has also chosen a name and presentation that keep the service recognizable across its main functions. That consistency helps when returning to the app after a few days away. I would still advise new users to move slowly during account setup and read each prompt instead of tapping through automatically. Financial apps are not places where speed is more valuable than understanding.
Good for people who prefer a guided routine
I think the app suits users who like a small number of familiar destinations. A regular routine might be to open the app after payday, confirm that incoming money arrived, check card activity, and then arrange a transfer to family. That workflow is easier to remember than navigating a large bank ecosystem with several layers of menus.
There is also a useful distinction between visual simplicity and true clarity. A clean screen can still be confusing if labels are vague or if an action hides important conditions. My practical advice is to treat every transfer screen as a confirmation step: check the recipient, amount, destination, and any displayed timing information before submitting. This habit is especially important when the transfer is intended for someone depending on the money for groceries, rent, or bills.
The app’s current version is 5.14.0, so users should keep an eye on changes after updates. Financial interfaces sometimes move buttons or rename sections even when the underlying service remains familiar. If a person relies on screen magnification, a particular text size, or a memorized sequence of taps, an update can temporarily make the routine harder. Taking a moment to explore after an update is sensible before attempting an urgent transfer.
Where readability can still become difficult
Banking language is inherently demanding. Terms connected with account verification, card use, transfers, and credit can carry consequences that are not obvious to a first-time user. MAJORITY’s focused design helps, but it cannot remove the need to understand what an action does. I would not recommend asking a family member to complete every step on your behalf without reviewing the details yourself, particularly when personal identity or payment information is involved.
For users with dyslexia, limited literacy, or limited English proficiency, the most helpful approach is to pair the app with a personal checklist written in plain language. For example: “check balance,” “review card payment,” “send family transfer,” and “save confirmation.” That turns the app into a repeatable process rather than a series of unfamiliar screens. It is a small adjustment, but in my experience it can make financial tasks feel much less intimidating.
Access across abilities and everyday situations
Motor comfort and touch interaction
Mobile banking is convenient because it avoids a trip to a branch, but it also assumes that a person can operate a touchscreen accurately. Users with tremors, reduced dexterity, joint pain, or difficulty making small gestures may find any phone-based financial task tiring. MAJORITY benefits from being used in short sessions: complete one task, verify it, and stop. That is safer and more comfortable than trying to organize an entire month of finances in one sitting.
My strongest practical tip is to prepare before opening the app. Have the recipient details, the intended amount, and a quiet place ready. This reduces the need to switch between apps, remember figures, or repeatedly tap through screens. It also lowers the risk of a motor mistake caused by rushing. For someone who uses a stylus or a larger device because precise touch is difficult, the same principle applies: slow confirmation is more important than fast navigation.
People who use voice control or other operating-system assistance should test the most important actions with a non-urgent task first. Banking actions can contain buttons or fields that are easy to confuse when read aloud, and a voice command that selects the wrong control may have real consequences. I would never use an unfamiliar accessibility setup for a large transfer without first checking how the app announces labels and confirmation messages.
Vision, hearing, and sensory load
Users with low vision may appreciate a focused account experience, but they still need to judge whether the app works comfortably with their phone’s text enlargement, contrast settings, and screen reader. I cannot responsibly promise that every accessibility setting will behave perfectly on every device. The better test is personal and concrete: can you read the balance, identify the transfer recipient, review the amount, and understand the final confirmation without assistance?
That test is more meaningful than simply asking whether an app looks modern. A financial app should support independent checking. If a user needs another person to read out the amount or confirm where money is going, privacy and control become concerns. In that situation, a trusted helper may be useful, but the account holder should remain involved in the final review whenever possible.
For people who are sensitive to visual clutter or notifications, MAJORITY’s narrower purpose may be less overwhelming than a broad financial super-app. On the other hand, anyone who depends on strong visual distinctions between completed and pending actions should take extra care to inspect transaction status rather than relying only on color or position. I recommend reading the wording of the status and keeping personal notes for transfers that matter.
Situational access for newcomers and families abroad
The app makes the most sense in a specific real-life scenario. Imagine someone who has recently moved to the United States, needs a debit card for daily spending, and wants to send part of a paycheck to relatives in another country. A conventional bank may feel difficult because of documentation expectations, unfamiliar processes, or the need to visit a branch. MAJORITY’s emphasis on a US account and debit card without an SSN can make the first step feel more approachable for that person.
That does not mean every newcomer will find the process effortless. Identity checks and account setup still require attention, and the user needs a phone they can operate reliably. But the app’s intended context is clearer than the generic “bank from anywhere” message used by many competitors. It acknowledges that banking and family support can be part of the same financial routine.
For an international family, the most useful workflow is to separate regular support from emergency support. Use a predictable schedule for ordinary transfers, keep the amount written down before starting, and leave enough time for the recipient to receive the funds before a deadline. Do not wait until the last minute simply because sending money from a phone feels instant. Transfer timing, recipient details, and verification steps can all matter.
Situational access also includes language and confidence. A person may be perfectly capable of managing money but uncomfortable with US banking terms. In that case, the app can be a helpful starting point if a trusted bilingual family member explains the process without taking control of the account. I would avoid sharing passwords or handing over a phone for routine use; assistance should improve understanding, not replace it.
Credit-building expectations need careful handling
The store summary mentions building credit, which may attract people hoping to establish a US financial history. That is an important reason to investigate the app, but it should not be interpreted as an automatic improvement in a person’s credit profile. Credit-related outcomes depend on the specific product terms, reporting arrangements, eligibility, and user behavior. Before relying on it for a housing or loan goal, I would read the in-app explanation carefully and confirm what actions actually contribute to credit-building.
This is one area where a traditional bank, secured card, or dedicated credit product may be a better fit for some users. MAJORITY can be appealing when the immediate need is access to an account and family transfers, while another service may offer clearer tools for long-term credit planning. The right choice depends on whether the user’s priority is access, remittances, everyday card spending, or building a broader financial record.
Remaining barriers before choosing it
The biggest limitation is that accessibility cannot be judged from a rating alone. A 4.7 average and around twelve thousand written reviews indicate strong user engagement, but they do not tell me whether the app works equally well with every assistive technology, device size, language preference, or motor limitation. Individual testing remains important, especially because this is a financial service rather than a casual utility.
Another barrier is dependence on a functioning phone. If the device is lost, damaged, shared, low on battery, or difficult to operate, access to the account may become inconvenient at exactly the wrong moment. I recommend keeping essential account and support information in a secure offline place, without recording sensitive credentials in an exposed notebook or message. Users should also know how they will contact support before an urgent problem occurs.
People who need joint household budgeting, complex bill management, extensive savings tools, or a full investment platform may outgrow MAJORITY’s focused approach. The app is not automatically the best replacement for a conventional bank. Someone with stable access to a local branch and a strong preference for in-person help may find the traditional option more reassuring. Likewise, a user who rarely sends money internationally may gain little from choosing a service whose identity is closely tied to that use case.
There is a social accessibility issue as well. Sending money home can create pressure to transfer more than is safe. The convenience of a phone-based workflow should not turn family support into an obligation that endangers the sender’s own rent, food, or emergency fund. I would set a personal limit before opening the app and treat that limit as part of responsible use.
Who should try it and who should look elsewhere
I would recommend MAJORITY to a newcomer who wants a straightforward US account and debit card, especially if sending money to family is part of everyday life. It also deserves consideration from users who find large banking apps confusing and prefer a service built around a smaller set of tasks. The free price makes it easy to explore, although users should still understand any terms attached to particular services before depending on them.
I would be more cautious for someone who needs extensive accessibility support but cannot test the app personally, or for a person who requires sophisticated household finances. In those cases, a bank with strong in-person assistance, a service with clearly documented assistive-technology support, or a specialized budgeting product may be more suitable. I would also steer away from using it as the only financial tool until the user has confirmed that account access, card use, transfers, and support fit their routine.
The Everyone age rating makes the app broadly approachable, but age suitability is not the same as financial suitability. A young adult, older user, or family member with limited banking experience may still need help understanding transfers and credit-related claims. A short guided practice, a written checklist, and careful review of confirmations can make the experience safer for people with different levels of confidence.
My inclusive verdict
MAJORITY succeeds because it connects a recognizable everyday need with a relatively focused mobile experience. Its strongest audience is not every banking customer; it is the person who wants practical US account access, a debit card, and a manageable way to support family abroad. In my experience, that focus can improve readability and reduce the intimidation often associated with financial services.
I also see meaningful limits. The app cannot guarantee comfortable access for every vision, hearing, motor, cognitive, or language need, and no mobile banking service should be trusted blindly with urgent transfers. Users should test their own device settings, confirm every important transaction, and decide whether the app’s focused design covers their longer-term financial plans.
Overall, I see it as a useful first banking option for the right context rather than a universal replacement for a full-service bank. If your main goal is to get started in the US and stay connected financially with relatives, MAJORITY is worth trying. If your priority is complex money management, branch-based reassurance, or highly specialized accessibility support, compare it carefully with alternatives before making it your primary account.


